Secure Inclave Casino Payments Australia
 Available in AU
Content
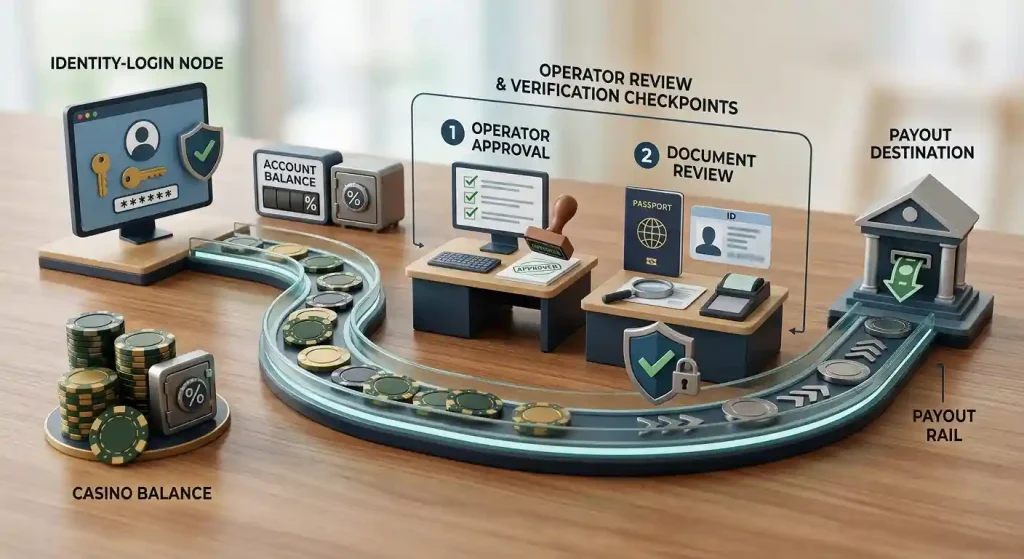
Inclave does not process casino deposits, hold player balances or send withdrawals. It is the identity and login layer. Once you enter a connected casino, that operator controls the cashier, supported currencies, payment methods, minimums, fees and withdrawal rules. That means there is no single “Inclave payment list” that applies across the network.
For Australians, the useful approach is to check the individual casino before depositing. Look for an AUD balance option, confirm whether the exact payment rail you want is available, and inspect the withdrawal route at the same time. PayID is a familiar Australian payment term, but its popularity in everyday payments does not prove that a particular casino accepts it. Treat PayID support as an operator-level fact that needs to be visible in that casino’s current cashier or terms.
Inclave Casino Banking: PayID Deposits and Cashier Processing
The most important banking fact is architectural rather than promotional. Inclave’s current terms describe it as an identity and login service and explicitly separate it from the casinos that use it. The service does not hold player money or process deposits and withdrawals. Each connected operator is a separate business with its own cashier and terms.
| Question | Inclave | Connected casino |
|---|---|---|
| Signs you in and carries verified identity | Yes | Receives authorised identity details |
| Holds your casino balance | No | Yes, under the operator’s account terms |
| Sets deposit methods and minimums | No | Yes |
| Sets withdrawal methods, limits and fees | No | Yes |
| Issues casino bonuses | No | Yes |
| Handles a delayed cash-out complaint | No | Yes |
This split matters because an easy Inclave login tells you nothing by itself about cashier quality. Two casinos using the same sign-in network can have different deposit rails, currency choices, limits and withdrawal procedures. Understanding deposit methods is only half the process; you must also review the Inclave casino withdrawal limits and payout times to avoid unexpected delays. For a broader explanation of that network structure, see the Inclave Australia guide.
AUD should be your first cashier check
If you fund an account from Australia, start by checking whether the casino can keep your balance in Australian dollars. An AUD wallet can make deposits, wagers, bonuses and withdrawals easier to read because you are not mentally converting every value. More importantly, it reduces the chance that an exchange-rate spread or conversion fee becomes an unnoticed cost.
Do not infer AUD support from an Australian-facing article, an Inclave country selector or a payment logo elsewhere on the web. The decisive evidence is the operator’s current cashier or account currency menu. Check the currency before the first deposit, because some operators lock the account currency after registration or treat a currency change as a support request.
Why PayID is relevant, but not a network feature
PayID deserves attention because it is now a mainstream account-to-account payment concept in Australia. The Reserve Bank of Australia’s 2025 Consumer Payments Survey, published in May 2026, found that around 80% of respondents knew PayID and around 50% had used it in the previous year. The RBA describes PayID as a way to address a bank transfer using a mobile number, email address or Australian Business Number rather than traditional account details.
That local familiarity is useful context when you assess a casino cashier. It is not evidence that Inclave supports PayID, because Inclave is not the cashier, and it is not evidence that every connected casino offers PayID. If you specifically want PayID, find it by name inside the operator’s logged-in cashier and read the operator’s current payment conditions before depositing.
A payment method can also appear only for some account types, currencies, locations or transaction directions. A deposit button does not automatically mean the same rail is available for withdrawal. This is why a cashier check should cover both money in and money out.
Do the withdrawal check before the deposit
The best time to discover a poor cash-out route is before money goes in. Open the withdrawal section, if the operator allows it before a funded transaction, and look for the available destinations, identity requirements, minimum cash-out, maximum limits, processing stages and any stated fees. Exact figures are operator-specific and can change, so this guide does not invent one network-wide payout speed or limit. Discover trusted operators with fast transactions on our premier Inclave gambling portal.
Also check whether the operator expects withdrawals to return to the original funding method. Payment-method matching is common in online financial controls, but the exact rule belongs to the casino. If the original route cannot receive a payout, the operator may require an alternative method and additional verification.
For a focused cash-out checklist, including who owns KYC and payout problems, use the withdrawals and payout checks guide.
Payment method and bonus eligibility are separate checks
Inclave does not issue casino bonuses. A connected operator controls the offer and its conditions. That means a payment method that works for a deposit can still be excluded from a promotion, or a bonus can have its own minimum qualifying deposit even when the cashier accepts a smaller transaction.
Before using a promotion, match three pieces of information on the same operator: the cashier method, the bonus terms and the account currency. Do not assume that a method qualifies just because the deposit succeeds. The detailed offer analysis belongs in the bonus terms guide, but the payment lesson is simple: confirm promotional eligibility before selecting the rail.
Fees and limits: where to look
Fees and limits are among the details most likely to become misleading when copied into a network-wide table. The operator can set deposit minimums, withdrawal minimums, transaction caps, frequency limits, processing charges and currency conversion rules. Those figures need current operator-level evidence.
- Deposit minimum
- Check the amount shown next to the selected method in the cashier and compare it with any bonus minimum.
- Deposit fee
- Check both the casino screen and your bank or wallet terms. A casino showing no fee does not guarantee that your payment provider charges nothing.
- Withdrawal minimum
- Read the operator’s withdrawal screen or payments terms before building a balance that could be awkward to cash out.
- Withdrawal cap
- Look for per-transaction and periodic limits. Do not rely on a figure from a different Inclave-connected brand.
- Currency conversion
- Identify which party performs the conversion and which exchange rate or fee applies.
Pre-deposit cashier checklist for Australians
- Confirm the operator. Know which casino business is taking the deposit. Inclave is only the login and identity layer.
- Confirm AUD. Check account currency, deposit currency and withdrawal currency.
- Confirm the exact method. If you want PayID, card, bank transfer or another rail, verify it in the casino’s current cashier.
- Inspect cash-out first. Find the withdrawal methods, minimums, limits, verification steps and any stated fees.
- Match the bonus rules. If you plan to claim an offer, make sure the payment method and amount qualify.
- Check name matching. Use payment accounts in your own name and read any operator rules on third-party payments.
- Save evidence. Keep the transaction confirmation and a dated copy of the terms that applied when you paid.
This process is more useful than asking for the “best Inclave payment method” because the sign-in network does not set the financial terms. The relevant comparison is always between the cashiers of the individual casinos you are considering.
Australian legal context belongs to the operator, too
Australia’s rules for online gambling services apply at the service and operator level, not because a site happens to use Inclave for identity. A shared login does not give a casino an Australian licence and does not turn separate operators into one regulated entity. When assessing a connected casino, keep payment convenience separate from legal and regulatory status.
That distinction also prevents a common mistake: using a familiar Australian payment term as a proxy for legitimacy. A cashier that offers an Australian-friendly rail still needs its own operator, licensing and legal-context checks. See the Australian legal context for that separate assessment.
What to do if a payment goes wrong
Send the problem to the party that controls it. If the issue is a deposit that has not credited, a withdrawal that has not been approved, a fee, a cashier limit or a disputed balance, contact the casino operator. Inclave’s terms place those matters with the casino. If you cannot enter the casino because the Inclave sign-in or identity verification itself is failing, that is an Inclave support issue.
When contacting the operator, include the transaction date, amount, method, reference number and the exact status shown in the cashier. Avoid sending full card numbers or unnecessary identity documents in an ordinary email or chat. Use the operator’s secure verification channel when documents are required.
How to compare two connected casino cashiers
A useful comparison does not start with the number of payment logos. Start with the full transaction path. One operator can look convenient at deposit stage but become less attractive once you compare account currency, cash-out routes, limits, verification and fees. A second operator can offer fewer deposit options yet provide a clearer withdrawal path. The better choice is the one whose entire cashier suits how you actually plan to fund and withdraw.
| Comparison point | What a strong cashier shows | What needs a second look |
|---|---|---|
| Currency | AUD is clearly selectable and consistently displayed | Conversion occurs without a clear explanation |
| Deposit rail | Method, minimum and any fee are visible before payment | A logo appears without usable terms |
| Withdrawal rail | Cash-out destinations and restrictions are easy to find | Withdrawal information is hidden or vague |
| Limits | Transaction and periodic caps are stated | Only a headline maximum is shown with no context |
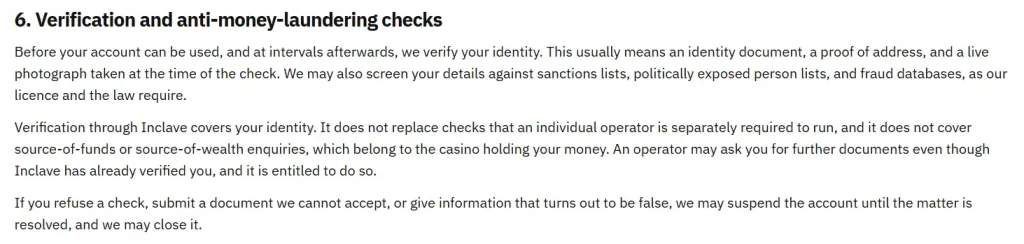
| Verification | The operator explains when extra checks can occur | The cashier implies shared identity removes all operator checks |
| Bonus interaction | Eligible payment methods are named in the offer terms | The deposit page and bonus terms appear inconsistent |
Do the comparison while both sites are open, preferably before creating a large balance. Record what each operator actually shows rather than relying on a third-party list that may combine several brands. This is especially important with Inclave-connected casinos because the shared login makes the front door feel similar even when the financial rules behind it are not.
Why payment logos are weak evidence on their own
A payment logo can tell you that an operator has integrated or promoted a method, but it does not answer the questions that matter to a specific account. Availability can depend on currency, location, account status, transaction direction and provider rules. The logo also does not tell you the minimum deposit, whether a promotion accepts the method, whether withdrawals return through the same rail, or whether a fee applies.
For PayID in particular, use the name as a prompt to investigate, not as proof. The RBA data shows why Australians recognise and use PayID in ordinary payments. Casino support is a separate commercial decision made by the operator. If the cashier does not show PayID for your account, the fact that PayID is widely used in Australia does not change that.
The strongest evidence is the combination of the live cashier, the operator’s current payments terms and the withdrawal screen. If those sources disagree, resolve the inconsistency before depositing. A familiar login should never replace a direct check of the business that will actually receive and return the money.
Bottom line
There is no universal Inclave cashier. Inclave can simplify identity and sign-in, but each connected casino independently controls deposits, withdrawals, currencies, fees, limits and bonus payment rules. For an Australian player, the strongest pre-deposit test is therefore operator-specific: confirm AUD, verify the exact payment rail, inspect the withdrawal route, and read the current terms. PayID’s popularity in Australia makes it a sensible item to look for, not a feature to assume.
This material was created by the Inclave Australia Guide team.
Related posts
Fast Inclave Casino Withdrawals Australia
Fast Inclave Verification and KYC Australia