Fast Inclave Casino Withdrawals Australia
 Available in AU
Content
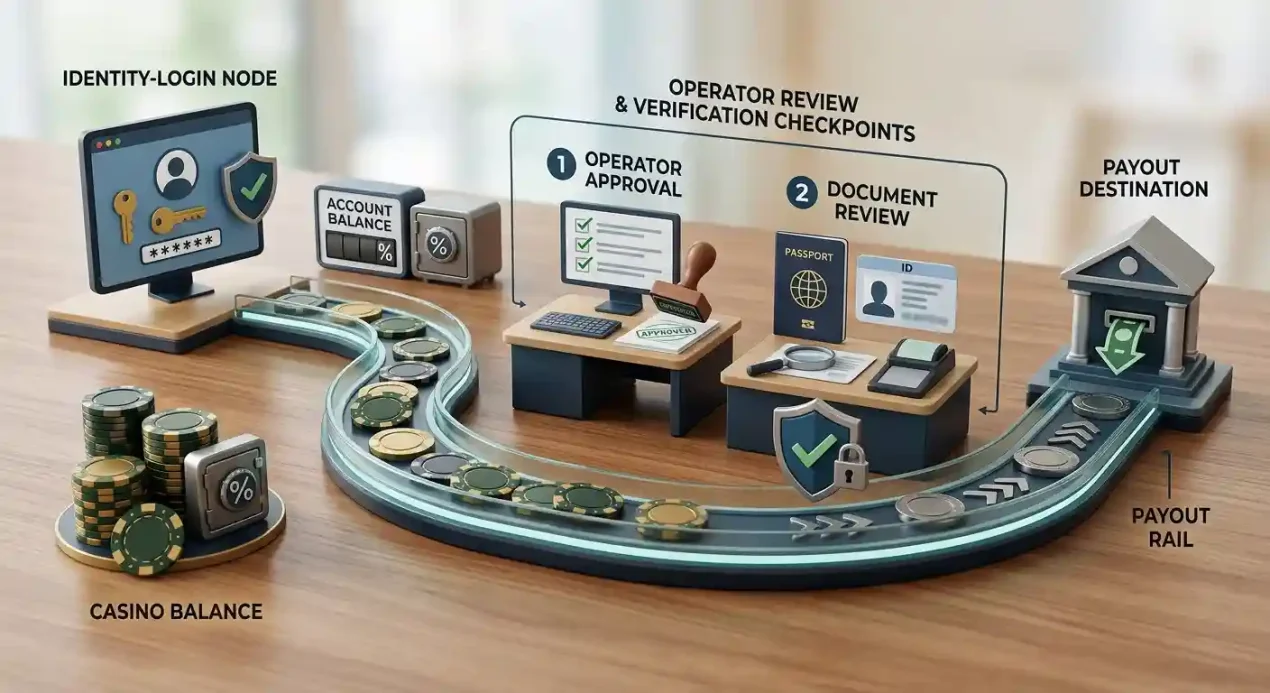
Inclave does not approve, process or send casino withdrawals. The individual casino controls the player balance and its cashier, so that operator sets the payout methods, approval process, limits, fees and transaction timing. There is no reliable network-wide “Inclave withdrawal time”.
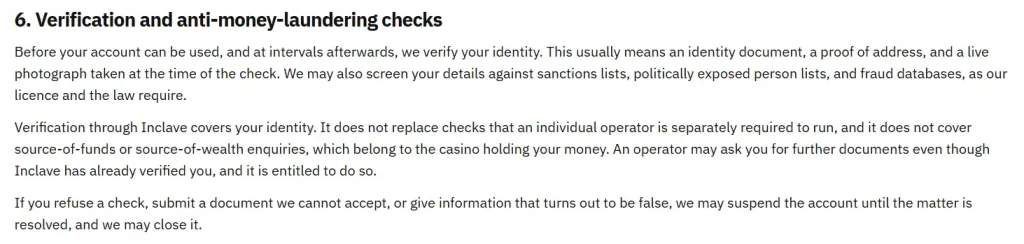
Inclave does have a role in identity verification. Its current terms describe identity-document, proof-of-address and live-image checks, and they make clear that a connected casino can still request additional verification or source-of-funds information. For Australians comparing connected casinos, the useful question is therefore not “How fast is Inclave?” but “What does this operator require before it releases a withdrawal?” Check that before depositing.
Inclave Casino Payout Steps: Withdrawal Limits and Verification Times
| Withdrawal issue | Responsible party | What to check |
|---|---|---|
| Balance and cash-out request | Casino operator | Cashier status and operator terms |
| Payout method | Casino operator | Available destinations and method-matching rules |
| Limits and fees | Casino operator | Current withdrawal screen or payments terms |
| Initial Inclave identity check | Inclave | Inclave verification status |
| Extra KYC or source-of-funds check | Casino operator | Operator request and secure upload channel |
| Login failure | Inclave | Account access and device approval |
Inclave’s terms are explicit that a delayed withdrawal is a matter for the casino, while a problem with Inclave login or identity verification belongs to Inclave. This division is the key to resolving problems efficiently.
KYC can happen before or during cash-out
Inclave verifies identity before an account can be used and can repeat checks later. Its terms currently describe an identity document, proof of address and a live photograph as the usual verification set. Its privacy policy also describes document images, proof of address and a selfie or short video as verification data.
That shared identity check does not eliminate operator KYC. Inclave’s terms state that an individual casino can run checks it is separately required to perform and can request further documents. Source-of-funds and source-of-wealth enquiries belong to the casino holding the money, not to Inclave.
For the document-level detail and the distinction between shared identity and operator checks, see KYC and verification. On a withdrawal page, the practical point is simpler: having a verified Inclave account does not guarantee that the casino will approve a cash-out without another review.
What can delay a payout?
There is no single delay list that applies to every connected casino, but several operator-controlled checks deserve attention. A pending withdrawal can remain with the operator while it verifies identity, reviews source-of-funds information, checks the destination method, applies its internal approval process, or resolves an account or bonus condition. Exact timing depends on the casino’s current terms and should not be copied from another brand.
- Reverification: the casino asks for fresh or additional identity evidence.
- Source of funds: the casino asks where deposited money came from and requests supporting evidence.
- Payment-method mismatch: the requested cash-out route differs from the method the operator requires.
- Account data mismatch: names, addresses or payment ownership details do not align.
- Bonus status: the operator checks whether a promotional balance has met its withdrawal conditions.
- Operator review: the withdrawal remains pending under that casino’s own approval workflow.
These are reasons to inspect operator rules, not a basis for guessing a universal processing time.
Limits and fees need operator-level evidence
Exact withdrawal minimums, daily or weekly caps, fees and processing windows are high-risk details because they can vary by operator, payment rail, currency and account status. This guide does not publish a made-up Inclave-wide figure. Inclave does not set those values.
Before depositing, open the casino’s withdrawal page or current payments terms and look for four separate numbers: minimum withdrawal, maximum per transaction, any periodic cap, and any fee. If a value is not displayed until login, treat it as unknown until you can see the cashier. Do not import a figure from another Inclave-connected casino.
For the broader deposit, AUD and PayID checks that come before this step, use the payments and cashier guide.
Pre-deposit payout checklist
- Open the withdrawal screen first. Do this before building a balance.
- Confirm the destination methods. Check whether the payment rail you plan to use can also receive withdrawals.
- Read limits and fees. Record the current values shown by that operator.
- Check verification status. Make sure your Inclave identity details are current and match the casino account.
- Expect operator KYC. A casino can still request extra documents or source-of-funds evidence.
- Check bonus conditions. If you accepted a promotion, verify that the balance is withdrawable under the operator’s rules.
- Use accounts in your own name. Name mismatches can create avoidable review work.
- Save the terms. Keep evidence of the withdrawal rules that were displayed when you deposited.
This checklist shifts attention from marketing claims to the part of the relationship that matters when you want your money back.
Bonus balances can add a separate withdrawal layer
Bonuses are issued by the casino, not Inclave. If a withdrawal is linked to a promotion, the operator’s bonus terms can affect whether the balance is eligible to cash out. That can include qualifying-deposit rules and other promotion-specific conditions. Exact wagering multipliers or expiry windows should be taken only from the current operator terms for the specific offer.
Do not ask Inclave to override a voided bonus or release a promotional balance. Its terms place bonus disputes with the casino. Use the bonus withdrawal conditions guide to separate promotion rules from the login layer.
Where to send a withdrawal problem
Start with the casino if the issue concerns a pending or rejected withdrawal, a missing balance, a payment destination, a fee, a cash-out limit, bonus eligibility or an operator document request. Provide the withdrawal reference, date, amount, method and status shown in the cashier. Use the casino’s secure upload process for sensitive documents.
Contact Inclave when the problem is specifically with signing in, approving a device, accessing the shared account or completing Inclave’s own identity check. This ownership rule prevents lost time between two support teams.
Australian readers should separate payout quality from the login network
Inclave can reduce repeated registration and identity friction across connected brands, but it does not standardise their financial operations. One connected casino’s withdrawal experience is therefore not proof of another’s. Compare the operator that holds the balance, its cashier rules and its regulatory position as separate factors.
The main Inclave casinos Australia guide explains how the shared login layer differs from casino-level operations. For cash-outs, keep that distinction front and centre: operator due diligence is more important than the shared sign-in technology.
Read a pending status as an operator workflow, not an Inclave timer
When a cashier shows a withdrawal as pending, the status belongs to the casino’s process. It can represent an internal approval queue, a verification hold, a payment-method review or another operator step. Inclave does not start or stop that timer because it does not hold the balance or send the payment. This is why a search for a universal Inclave payout time can be misleading.
Instead, capture the status shown by the casino and compare it with that operator’s stated withdrawal process. If the operator publishes separate stages such as requested, approved and sent, identify which stage applies. If no timeline is stated, ask the casino support team for the status of the specific transaction rather than asking Inclave for a network estimate.
Prepare for a clean operator verification request
If a casino asks for additional KYC or source-of-funds material, treat it as a separate operator request even if Inclave already verified your identity. Read exactly what the casino asks for, use its secure upload channel, and make sure the account details match the documents. Do not send extra sensitive information that was not requested.
Keep a record of what you submitted and when. If the operator asks for a replacement document, note the reason and provide the corrected item through the same secure process. A clean record helps if you later need to explain why a withdrawal remained under review. It also makes it easier to distinguish an Inclave identity problem from a casino-level financial-compliance check.
Before depositing at another connected brand, remember that operator KYC can differ. Shared identity can reduce repeated verification friction, but Inclave’s current terms expressly preserve the casino’s right to perform checks it separately requires.
A simple record-keeping habit
Keep the withdrawal reference, the operator terms you relied on, and any support case number until the payment reaches you. That small record makes later follow-up much easier.
Bottom line
An Inclave casino withdrawal is really an operator withdrawal from a casino that happens to use Inclave for identity and login. The operator controls approval, methods, limits, fees and timing. Inclave verifies identity, but the casino can still run additional KYC and source-of-funds checks. Before depositing, inspect the withdrawal screen, confirm the route you can use, record the current limits and fees, and understand which support team owns each possible problem.
This material was created by the Inclave Australia Guide team.
Related posts
Fast Inclave Verification and KYC Australia
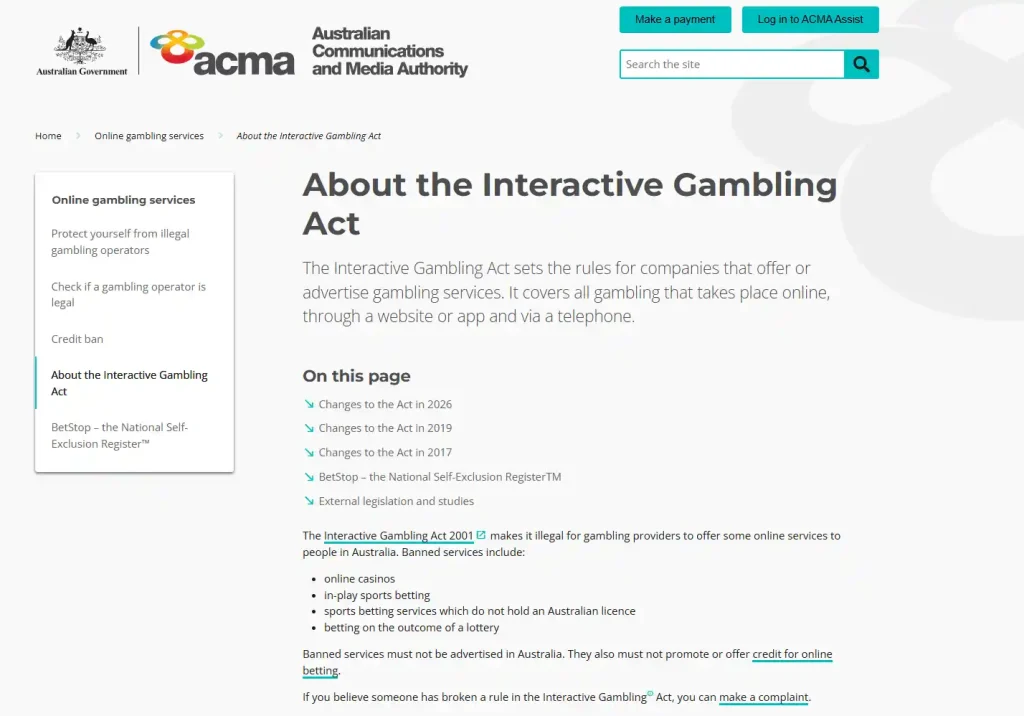
Verified Inclave Casino Safety Australia